The best banks for digital nomads are the ones that stay out of your way abroad: no foreign transaction fees, free (or refunded) ATM withdrawals, and an app you can run from anywhere. For most Americans, that means pairing a brokerage-linked checking account like Fidelity or Charles Schwab with a multi-currency account like Wise. Below is how the eight strongest options compare in 2026, and which combination fits which kind of traveler.
In this guide
Quick picks
- Best overall for ATM cash: Fidelity Cash Management Account — refunds ATM fees worldwide, same day.
- Best checking account for travelers: Schwab Bank Investor Checking — unlimited worldwide ATM rebates, no foreign transaction fees.
- Best for holding and spending other currencies: Wise — 40+ currencies, conversions from 0.23%.
- Best simple backup: Capital One 360 Checking — no foreign transaction fee and no Capital One fee at foreign ATMs.
- Best for UK and EU residents: Starling (UK) or N26 (eurozone).
What makes a bank good for digital nomads?
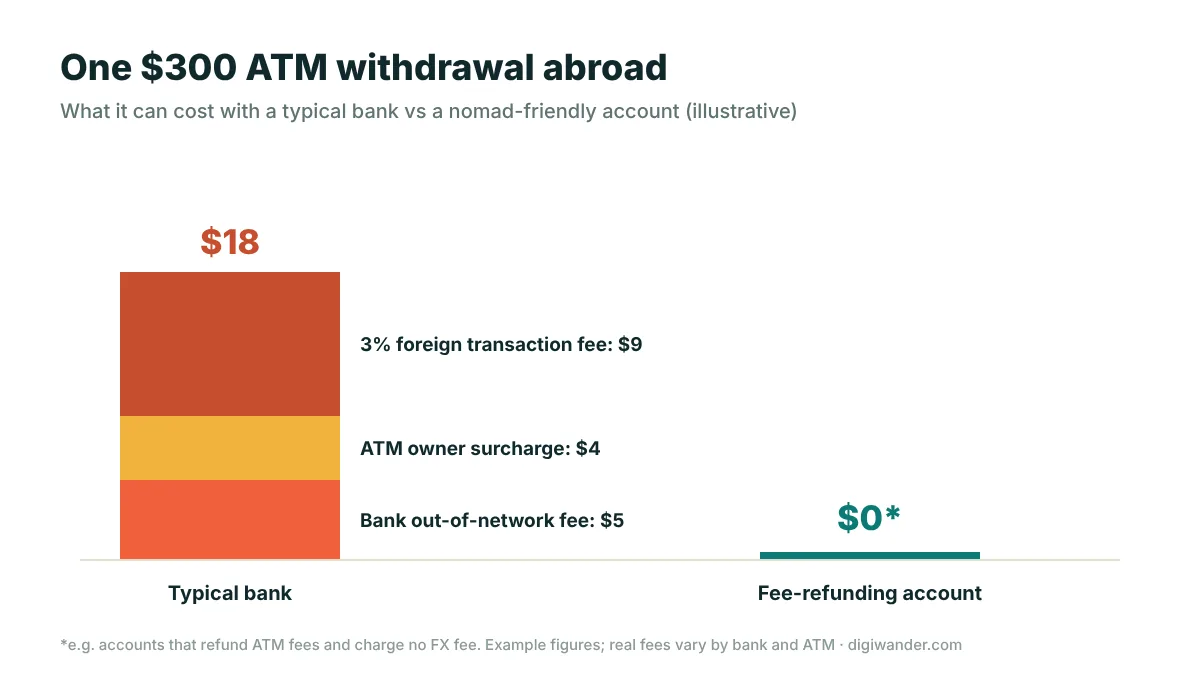
A normal high-street bank can quietly cost a nomad hundreds of dollars a year. Three fees do most of the damage:
- Foreign transaction fees. Many US debit cards add around 1–3% to every purchase made in another currency.
- Out-of-network ATM fees. Your bank may charge a flat fee for using a foreign ATM — and the ATM owner usually adds its own surcharge on top.
- Bad exchange rates. Dynamic currency conversion (when an ATM or card terminal offers to charge you “in your home currency”) can add a hidden markup. Always choose to pay in the local currency.
Beyond fees, nomads should look for an account that does not freeze when you log in from a new country, that lets you receive verification codes without a local SIM (app-based authentication is ideal), and that will keep working if you have no fixed home address for long stretches. Our guide to alternative bank solutions for digital nomads covers the address problem in detail.
Comparison table
| Account | Monthly fee | Foreign transaction fee | Foreign ATM fees | Best for |
|---|---|---|---|---|
| Fidelity Cash Management | $0 | None | Refunded worldwide (Visa, Plus, Star ATMs) | US travelers who use cash |
| Schwab Investor Checking | $0 | None | Unlimited rebates, credited monthly | US travelers, full-time nomads |
| Betterment Checking | $0 | Visa 1% fee reimbursed | Operator surcharges reimbursed | US users who like app-first banking |
| Capital One 360 Checking | $0 | None | No Capital One fee; ATM owner fees not refunded | Backup card |
| Wise | $0 (US card $9) | None on card; conversion from 0.23% | First $250/month free (US), then fees | Holding 40+ currencies |
| Revolut (US) | $0–$16.99 | Fair-use limits by plan | Free in-network; 2% out-of-network on Standard | Budgeting, frequent FX |
| Starling (UK) | £0 | None | No Starling fee abroad | UK residents |
| N26 (EU) | From €0 | No N26 fee | 1.7% outside eurozone on Standard | Eurozone residents |
Fees as published by each provider and checked in October 2026. ATM owners can still add their own surcharge.
The 8 best banks for digital nomads in 2026
1. Fidelity Cash Management Account
Best for ATM cashFidelity’s Cash Management Account works like a checking account but sits inside a brokerage. It is the closest thing to “free cash anywhere” for US citizens: Fidelity automatically reimburses fees other institutions charge at ATMs showing the Visa, Plus or Star logos, and the refund posts the same day the fee is charged. Fidelity also removed the 1% foreign transaction fee from its debit card in August 2024.
Pros
- Worldwide ATM fee refunds
- No monthly fee or minimum
- No foreign transaction fee
Cons
- Needs a US address and SSN to open
- Not a traditional bank branch network
2. Charles Schwab Bank Investor Checking
Best checking account for travelSchwab Investor Checking has been the default nomad account for years. It charges no monthly fee, no minimum balance and no foreign transaction fees, and it offers unlimited rebates on eligible ATM withdrawals worldwide, credited at the end of each statement cycle. The catch: you must also open a linked Schwab One brokerage account (also free, no minimum).
Pros
- Unlimited worldwide ATM rebates
- No FX fee on the debit card
- Strong app and 24/7 support
Cons
- Requires a linked brokerage account
- Rebates arrive monthly, not instantly
- Very low interest on checking
3. Betterment Checking
App-first US optionBetterment Checking (banking provided by nbkc bank, Member FDIC) has no monthly fee or minimum balance. It reimburses ATM operator surcharges worldwide and also reimburses the 1% Visa foreign transaction fee on international purchases and withdrawals. It is a good alternative if you already invest with Betterment or want a clean, simple app.
4. Capital One 360 Checking
Best backup cardCapital One 360 charges no foreign transaction fee and adds no Capital One fee at international ATMs. Unlike Schwab and Fidelity, it does not refund the ATM owner’s surcharge — so it is best as a backup card in a separate bag, not your main cash card.
5. Wise
Best for multiple currenciesWise is not a bank, but it is the most useful money tool most nomads own. You can hold and convert more than 40 currencies at the mid-market rate plus a transparent fee (from about 0.23%), and the debit card spends in the local currency without foreign transaction fees.
In the US, the physical card costs $9 and the first $250 of ATM withdrawals each month is free. Wise also gives you local account details in several currencies — handy for getting paid by clients abroad.
Pros
- Real exchange rate, low fees
- Local account details in major currencies
- Works well alongside a US bank
Cons
- Limited free ATM allowance
- Not a bank — check how your balance is protected in your country
6. Revolut
Best for frequent currency exchangeRevolut is popular with nomads who exchange money often. In the US, the Standard plan is free, Premium costs $9.99/month and Metal $16.99/month. Standard includes $1,000 of fee-free currency exchange per month (then 0.5%) and charges a 1% markup on weekend exchanges; paid plans raise or remove those limits and include $800–$1,200 a month of free out-of-network ATM withdrawals.
7. Starling Bank (UK residents)
Best for UK nomadsStarling is a fully licensed UK bank with no fees for card spending or ATM withdrawals abroad. Card payments use the Mastercard exchange rate, and overseas ATM withdrawals are limited to £300 a day. If you are a UK resident heading off on a long trip, it is one of the simplest “set and forget” options.
8. N26 (eurozone residents)
Best for EU nomadsN26 adds no extra fee to foreign-currency card payments. On the free Standard account, ATM withdrawals outside the eurozone cost 1.7% of the amount; higher plans such as Go and Metal make those withdrawals free. It is a strong fit for EU citizens who spend most of their time in Europe.
The best banking setup for most digital nomads
No single account does everything. The setup that works for most US-based nomads looks like this:
- Main account: Schwab Investor Checking or Fidelity CMA for salary deposits and ATM cash.
- Currency account: Wise for holding euros, pounds or other currencies and receiving payments from abroad.
- Credit card: a card with no foreign transaction fee — ideally one that also includes travel insurance.
- Backup: a second debit card (Capital One 360 or Revolut) kept separately in case your main card is lost or blocked.
Before you open accounts, work out your monthly budget with our guide on how much money you need to become a digital nomad.
Tip: Tell each bank you are travelling (most let you do this in the app) and turn on push notifications, so you can unblock a card in seconds if a fraud check is triggered.
What if you are not from the US?
Fidelity, Schwab, Betterment and Capital One are realistically only available to US residents. If you live elsewhere, start with a local bank that has low foreign fees (such as Starling in the UK or N26 in the eurozone) and add Wise or Revolut for currency. Freelancers paid by foreign clients should also read our guide to the best alternative bank accounts for receiving international payments.
Frequently asked questions
What is the best bank for digital nomads?
For US citizens, Fidelity’s Cash Management Account and Charles Schwab Bank Investor Checking are the strongest choices because they charge no foreign transaction fees and refund ATM fees worldwide. Most nomads pair one of them with Wise for holding other currencies.
Which bank refunds ATM fees worldwide?
Fidelity reimburses ATM fees charged by other institutions at Visa, Plus and Star ATMs, crediting the refund the same day. Schwab Bank Investor Checking offers unlimited worldwide ATM rebates, credited at the end of each statement cycle.
Can I open a US bank account as a digital nomad without a US address?
Most US banks require a US residential address and Social Security number. Non-US nomads usually use Wise, Revolut or a bank in their home country instead; US citizens abroad often keep a US address through family or a virtual mailbox, but should confirm what their bank accepts.
Is Wise a bank?
Wise is a regulated money services provider, not a traditional bank in most countries. It is excellent for holding and converting currencies, but keep at least one account at a fully licensed bank as well.
How many bank cards should a digital nomad carry?
At least three: a main debit card, a backup debit card on a different network (Visa and Mastercard), and a credit card with no foreign transaction fee. Keep them in separate places so one lost wallet does not leave you without money.
Sources
Last updated . Fees, rules and prices change often — confirm current details with the official source before you act. This article is for information only and is not financial advice. See our disclaimer.